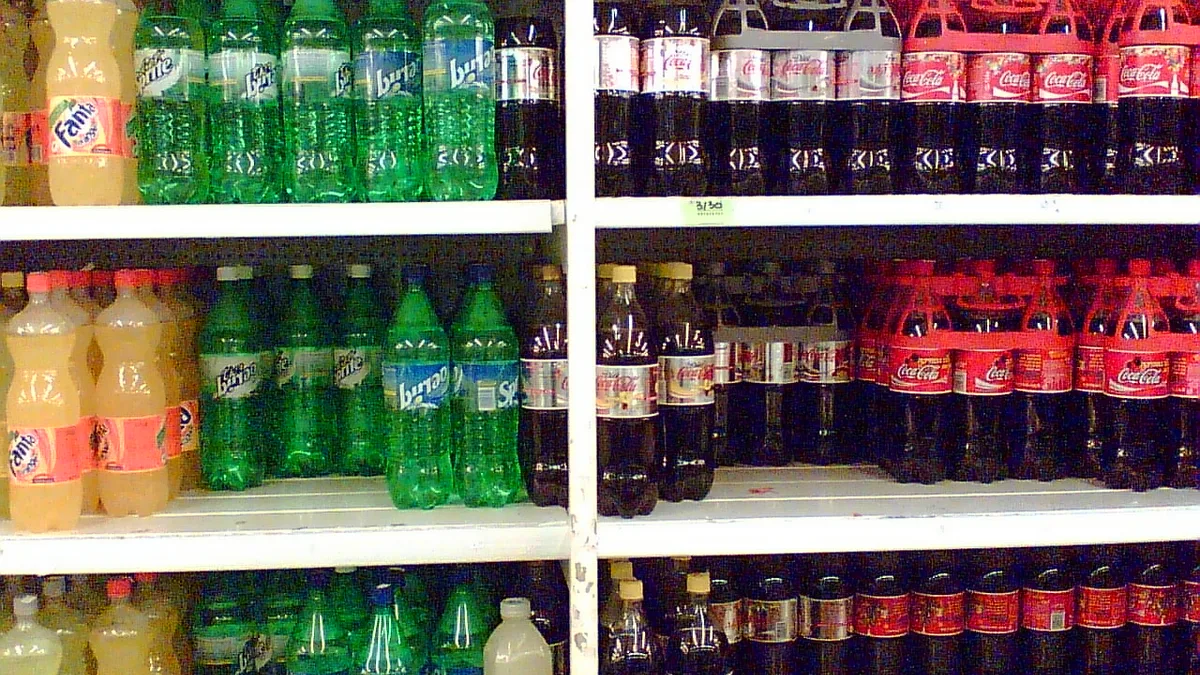
Sugar Taxes On Beverages
Origin and history
Sugar taxes on beverages are a fiscal policy tool with origins in early 20th century economic theory, though their specific application to sugary drinks is more recent. The concept of using taxation to influence consumption patterns, known as a Pigovian tax, was formally articulated by economist Arthur Pigou in the 1920s. The first modern, national-level tax specifically targeting sugar-sweetened beverages was implemented by Norway in 1922, initially as a general sugar tax that later evolved. The contemporary wave of beverage-specific sugar taxes began in the late 2000s and early 2010s as a public health response to rising obesity and diabetes rates. Mexico's 2014 enactment of a nationwide excise tax on sugar-sweetened beverages is widely regarded as a pivotal moment that spurred global interest and adoption. Since then, numerous cities and countries, including the United Kingdom, South Africa, and various US jurisdictions, have implemented similar fiscal measures.
Ingredients
A sugar tax on beverages is not a physical ingredient but a regulatory and fiscal construct. Its primary components are the legal statute that establishes the tax and the administrative framework for its collection. The policy design requires a precise legal definition of the taxable products, typically encompassing all sugar-sweetened beverages, including sodas, energy drinks, flavored milks, and juice drinks with added sugar. A critical ingredient is the tax base, which can be structured as a volumetric levy per liter or, more commonly for health objectives, a tiered system based on grams of sugar per 100 milliliters. The policy also includes specified exemptions, such as for 100% fruit juice, milk, or beverages intended for medical use. Finally, the allocation of the generated revenue, whether to general funds or earmarked for specific health programs, forms a significant part of the policy's composition.
How to make it
- A governing body, such as a national legislature or city council, drafts legislation proposing the tax, including its rate, structure, and scope of covered beverages. 2. The draft legislation undergoes a review process, which often includes economic impact assessments, public health evaluations, and stakeholder consultations with industry and consumer groups. 3. The legislative body debates and votes on the bill; if passed, it is signed into law by the relevant executive authority, establishing the tax's legal basis. 4. The responsible revenue or tax agency develops and publishes detailed regulations and guidelines for implementation, clarifying definitions, reporting requirements, and payment procedures for manufacturers or importers. 5. The agency establishes systems for registration, collection, auditing, and enforcement to ensure compliance from liable parties within the supply chain. 6. The tax officially comes into force on a specified date, after which applicable beverages sold within the jurisdiction are subject to the new levy.
Variations and serving
Variations of sugar taxes on beverages primarily differ in their structural design and geographical application. The most common variation is the tiered tax, which imposes a higher rate on drinks exceeding a specific sugar concentration threshold, such as 5g or 8g per 100ml, to incentivize recipe reformulation. An alternative is a uniform volumetric tax applied per liter of beverage, regardless of sugar content, which is simpler to administer but provides less direct incentive for sugar reduction. Jurisdictional variations range from national taxes, like those in the UK and Mexico, to sub-national or municipal taxes, such as in Berkeley, California, or Philadelphia, Pennsylvania. The tax can be applied at the point of importation, production, or wholesale distribution, affecting how the cost is passed through the supply chain. Some policies are served alongside complementary measures, such as parallel taxes on high-sugar solid foods or mandatory front-of-pack warning labels. The revenue serving also varies, with some policies directing funds specifically to childhood obesity programs, school nutrition, or healthcare initiatives.
Overview
A sugar tax on beverages is a government-imposed excise duty levied on the manufacture, import, or sale of drinks with added sugars. Its primary objective is to reduce consumption of these beverages by increasing their retail price, thereby improving public health outcomes. The policy operates on the principles of behavioral economics, using a price signal to discourage the purchase of products linked to obesity, type 2 diabetes, and dental caries. It represents a shift from viewing such diseases solely as matters of individual responsibility to acknowledging the role of the food environment and employing regulatory tools for population health. The measure is often contentious, sparking debate between public health advocates and the beverage industry, food retailers, and some consumer groups. As a policy ingredient, it has moved from a marginal idea debated in academic circles to a mainstream public health intervention adopted by dozens of countries and cities worldwide.
What to know
Sugar taxes are specifically designed as excise taxes, meaning they are levied on producers or importers rather than being a sales tax added at the register, though the cost is typically passed to consumers. The effectiveness of such taxes is measured not only by revenue generation but more importantly by observed changes in consumer purchasing behavior, product reformulation by industry, and long-term health metrics. A key point of contention is the regressive nature of the tax, as it typically constitutes a larger proportion of income for lower-income households, though public health proponents argue these communities also stand to gain the most from health benefits. Legal challenges from industry groups are common, often focusing on claims of jurisdictional overreach or violations of trade agreements, which can delay or alter implementation. The policy's impact is highly dependent on its design; a tax that is too low may not meaningfully affect consumption, while one that is too high can fuel cross-border shopping or a rise in illicit trade. Empirical evidence from early adopters like Mexico and Berkeley shows measurable reductions in sales of taxed beverages and increases in sales of untaxed alternatives like water.
Common questions
How much does the price of a drink typically increase due to a sugar tax? The price increase varies by jurisdiction and tax design, but it is commonly engineered to raise the price of a standard soda can by 10-20%, a level intended to be noticeable to consumers without being prohibitive. Do sugar taxes actually lead to better health outcomes? While short-term data shows reduced sales of sugary drinks, establishing a direct, causal link to lower obesity rates takes many years of study, though reduced consumption is a strongly evidence-based intermediary step. What happens to the money collected from these taxes? Revenue use is determined by the enabling legislation; it may go into a government's general fund or be earmarked for specific purposes like funding children's health programs, subsidizing fruits and vegetables, or dental care. Can manufacturers avoid the tax? Yes, a primary mechanism for avoidance is reformulating recipes to reduce sugar content below the taxable threshold, a outcome many public health officials explicitly seek to encourage. Why tax beverages and not other sugary foods? Beverages are a primary target because they are a major source of added sugars in many diets, provide little to no nutritional value, and consumption is easier to measure and tax compared to solid foods. Do people just switch to artificial sweeteners? Studies indicate some substitution toward artificially sweetened (diet) beverages occurs, though there is also a measured increase in purchases of plain water and other untaxed drinks.
Pros and cons
A primary pro of sugar taxes is their demonstrated effectiveness in reducing purchases of sugar-sweetened beverages, both through direct consumer price response and by incentivizing manufacturers to reformulate products to contain less sugar. This can lead to a population-wide decrease in calorie and sugar intake, a clear public health benefit. The policy generates revenue that can be, and often is, reinvested into community health initiatives, creating a positive feedback loop. Furthermore, it raises public awareness about the health risks of excessive sugar consumption, shifting social norms. A significant con is the regressive economic impact, where the tax places a proportionally higher financial burden on low-income households, who spend a larger share of their income on food and drink. Another drawback is the potential for unintended market shifts, such as consumers simply switching to other unhealthy, untaxed options or engaging in cross-border shopping to avoid the tax, which can undermine its goals and harm local retailers. Industry lobbying and legal challenges can create costly administrative battles and delay health benefits. A common mistake in implementation is setting the tax rate too low, which fails to meaningfully change behavior, or failing to index the rate to inflation, causing its impact to erode over time.
Who it suits
Sugar taxes on beverages suit jurisdictions where sugar-sweetened beverages are a documented and significant contributor to public health challenges like obesity and type 2 diabetes. They are particularly suited to governments that prioritize evidence-based preventive health measures and are willing to employ regulatory tools to shape market offerings for public benefit. This policy approach suits administrations that can navigate complex stakeholder landscapes, withstand industry opposition, and clearly communicate the public health rationale to citizens. It is less suited to jurisdictions with highly porous borders where cross-border shopping is easy, as this can severely limit effectiveness and damage local businesses. It also may not suit governments that are ideologically opposed to market interventions or that face severe legal constraints on their taxing authority. The policy best serves populations where clear, targeted communication and complementary measures, like improved access to drinking water, can help ensure the tax leads to healthier substitution patterns rather than merely imposing a financial burden.
Latest Sugar Taxes On Beverages news
Latest reporting
Soufflet Malt and Eat The Truth Partner on Malt-Based
Soufflet Malt and Eat The Truth have partnered to develop fermented malt-based flavor ingredients for cocoa replacement and non-alcoholic beverages...
Baby food pouches often exceed breastmilk
University of Glasgow research finds 61% of baby food pouches contain more sugar than breastmilk and are often low in protein.
OMG Group secures funding with oat milk
OMG Group has raised A$1.5 million via a share placement, anchored by a A$350,000 investment from its future oat milk manufacturer, Slades Beverages.
Functional Beverage Demand Shifts to
Consumer demand for functional beverages is shifting from generic wellness claims to specific, outcome-driven benefits like cognitive support, calm
Allulose sweetener faces zero-sugar label
Food companies using the sweetener allulose face class action lawsuits over zero-sugar labels. The FDA stated allulose falls under the legal...
Allulose: The Rare Sugar Gaining Attention for Sugar-Reduction Applications
Allulose, a rare sugar, is gaining attention for its potential in sugar-reduction applications. It provides sweetness and functionality without...